
Average Settlement for a Car Accident Back or Neck Injury in Florida
Written by the Hughes and Barnard Law Firm, PA marketing team and reviewed by Attorney Howard Hughes to ensure quality and accuracy.
There’s no single “average” figure that means much here. A whiplash strain that clears up in a few months of physical therapy might resolve for a few thousand dollars. A herniated disc that needs injections or surgery can settle well into six figures. The gap between those two outcomes is exactly why a number pulled from a generic online calculator rarely matches what a real claim is worth — what matters is the injury itself, how it was treated, and how much insurance is actually available to pay for it.
Why the Injury Type Sets the Range
Back and neck injuries from car accidents generally fall into a few categories, and each settles differently:
- Soft tissue strains and sprains (whiplash). The most common car accident injury. Usually treated with physical therapy or chiropractic care over a few weeks to a few months. Settlements are typically the lowest of the three categories, but a well-documented case with ongoing symptoms is still worth pursuing.
- Herniated or bulging discs. Often confirmed by MRI, sometimes treated with injections, occasionally surgery. Because there's objective imaging tying the injury to the crash, these claims tend to settle noticeably higher than soft-tissue-only cases.
- Fractures and spinal injuries. The most serious category, and the one most likely to involve permanent impairment. These carry the highest settlement ranges, but also the most complex, longest-running claims.
The Factors That Actually Move the Number
Within each category, a handful of things determine where a specific case lands:
- How consistently you were treated. Gaps in treatment give an insurance adjuster room to argue your injury wasn’t serious, or wasn’t caused by the crash. Florida also requires PIP-covered treatment to start within 14 days of the accident to preserve those benefits in the first place.
- What the imaging shows. An MRI showing a disc herniation carries more weight than a normal exam with only reported pain.
- Documented wage loss. Pay stubs and a doctor’s note restricting your work make lost income concrete instead of an estimate.
- The at-fault driver’s insurance limits. Florida’s minimum liability limits are lower than most people assume, and they set a practical ceiling on what’s available, regardless of how serious the injury is.
- Shared fault. Since March 2023, Florida follows a modified comparative negligence rule: if you’re partially responsible, your recovery is reduced by your percentage of fault, and if you’re found more than 50% at fault, you recover nothing at all. This makes how fault gets assigned far more consequential than it used to be.
What Changes When a Lawyer Is Involved
Insurance adjusters evaluate your claim against their own internal ranges, not against what you actually need for ongoing care or lost income — which is a big part of why represented claimants tend to recover more than the same injury handled alone. Hughes & Barnard has recovered $150M+ for injured clients across Florida to date (individual results depend on the specific facts of each case; see our case results for examples), and our Port St. Lucie car accident lawyers and Jupiter car accident attorneys build that documentation from day one, rather than after the insurance company has already made up its mind about your case.
How Insurance Companies Evaluate These Claims
Most insurers still lean on some version of a formula: total medical bills multiplied by a factor tied to injury severity, plus documented wage loss. It’s a useful starting point for them, and a poor one for you, because it treats a $3,000 course of physical therapy for a strain the same way it treats $3,000 in urgent-care bills for an injury that later requires surgery. The multiplier moves with perceived severity, not with what you’ll actually need going forward.
That’s also why the adjuster’s initial number often looks reasonable on paper and still falls short. It’s built from bills that already happened, not from future treatment your doctor expects, lost earning capacity if you can’t return to the same physical work, or the simple fact that chronic pain doesn’t show up on an invoice.
Common Mistakes That Reduce a Claim’s Value
A handful of avoidable missteps show up again and again in cases that settle for less than they should have:
- Waiting to see a doctor. Even a few days' delay gives an adjuster room to argue something else caused the injury.
- Stopping treatment once the pain eases. Insurers read gaps as evidence the injury wasn't serious, even when the real reason was a scheduling conflict or a copay.
- Posting about the accident, or about anything physical, on social media. A photo of you at a birthday party can be used to argue you're exaggerating, regardless of context.
- Giving a recorded statement to the other driver's insurer before speaking with a lawyer. Casual, imprecise language in the moment can be replayed later as an admission.
- Accepting the first offer. Early offers are almost always calculated before your full treatment picture exists.
Soft Tissue vs. Disc Injury: A Closer Look at Documentation
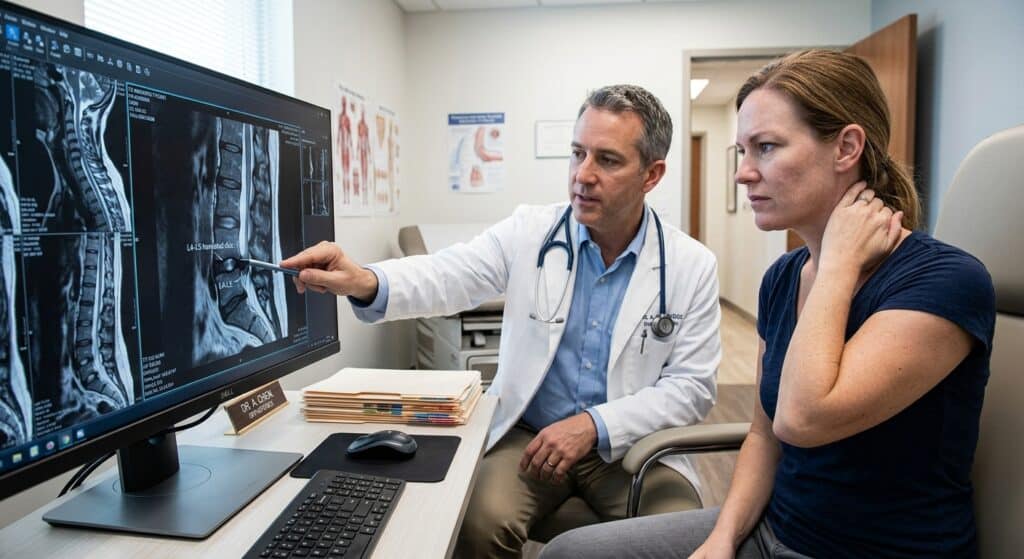
The difference between a soft tissue claim and a disc injury claim often comes down to what the medical record actually shows, not just what you feel. An X-ray typically shows bone, not soft tissue, so a normal X-ray after a whiplash injury doesn’t mean nothing is wrong; it means the wrong test was ordered to find it. An MRI is what actually confirms a herniated or bulging disc, and a specialist’s referral, rather than a single urgent-care visit, tends to carry more weight with an adjuster reviewing the file. None of this is about running up medical bills unnecessarily; it’s about making sure the record reflects what’s actually happening in your body, since a settlement can only be built from what’s documented.
Why Documentation Timing Matters as Much as Content
Two claimants with identical injuries can end up with very different settlements simply because one saw a doctor the same week and the other waited a month. Insurers weight recency heavily: a same-week visit reads as a direct response to trauma, while a delayed visit invites questions about what happened in between. This is one of the few parts of a claim’s value that’s completely within your control from day one.
FAQ
Is there a "typical" settlement for a back or neck injury?
It helps significantly, since it gives an objective, documented link between the crash and the injury, but it isn’t automatic. Treatment history, wage loss, and available insurance still factor in.
How does being partially at fault affect what I can recover?
Under Florida’s modified comparative negligence rule, your recovery is reduced by your percentage of fault, so being 20% at fault generally reduces your recovery by 20%. But if you’re found more than 50% at fault, you’re barred from recovering anything, which is why insurers push hard to assign fault to you.
Is there a deadline to get treatment after the crash?
Yes. Florida requires PIP-covered treatment to begin within 14 days of the accident to remain eligible for those benefits, separate from the overall statute of limitations for filing a claim.
What's the best first step if I'm still dealing with pain weeks after the crash?
A free case evaluation with a Port St. Lucie or Jupiter car accident lawyer, before you give the insurance company a recorded statement or accept an early offer.
Can a settlement be reopened if my injury gets worse later?
Generally, no. Once a personal injury settlement is signed, it’s final, which is exactly why it’s important to have a clear picture of your prognosis, not just your current symptoms, before agreeing to a number.
What if I had a pre-existing back or neck condition?
You can still recover for the portion of your injury the crash caused or worsened, even with a prior condition. Insurers will scrutinize this closely, so records showing your condition before and after the crash matter more than usual.
How long does it typically take to reach a settlement?
It varies with how long treatment takes and how much is at stake, but most claims aren’t ready to settle until your treatment has stabilized enough for a doctor to estimate what, if anything, comes next.
Does it matter which insurance company I'm dealing with?
It can. Some insurers are known for settling reasonably, others for contesting nearly everything, but either way the same documentation standards apply to build the strongest possible claim.
What if the insurance company says my treatment was excessive?
That’s a common tactic, and it’s exactly the kind of dispute a personal injury attorney is equipped to push back on, using your treating doctor’s own notes rather than the insurer’s opinion.
Recent Posts